

Afterpay: Pay over time
by Afterpay
4.0
- Safety
- 100% Safe
- Category
- Shopping
- Ratings
- 4.0
- Price
- Free
- Download
- 10.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
Afterpay is a shopping app built around one clear idea: split an eligible purchase into scheduled payments instead of paying the whole amount at checkout. I found that this focus makes it easy to understand, but it also demands a little more discipline than a normal shopping app. The useful question is not simply whether paying later sounds convenient; it is whether the payment schedule fits comfortably into your existing budget.
Developed by Afterpay, the app is free to download and is available for everyone according to its age rating. It belongs in the shopping category rather than acting like a general bank or budgeting tool. That distinction matters. I would use it to manage a planned purchase at participating stores, not as a replacement for checking my balance, tracking monthly expenses, or building an emergency fund.
How Afterpay’s pay-over-time approach feels in everyday use
I’d use this section to look beyond the convenience of splitting a purchase and focus on the moments when the app needs a reliable connection, especially while checking a schedule or completing checkout. That makes it easier to judge where a little preparation helps, and where it’s wiser to wait rather than rush a payment decision.
The capability is simple, but the timing matters
The main attraction is the ability to buy something now and spread the cost across flexible payments intended to fit a budget. In practice, the app changes the moment when money leaves your account. Instead of one large checkout payment, you deal with several smaller scheduled amounts. That can make a necessary purchase feel more manageable, especially when the full cost would otherwise collide with rent, groceries, or another fixed bill.
My strongest advice is to think of the feature as a payment-planning tool, not extra spending power. The total purchase still matters, and the later payments do not disappear because the first one felt affordable. Before confirming anything, I would look at the complete schedule and compare every installment with bills already due during that period.
This is where Afterpay differs from an ordinary retailer checkout. A standard card payment ends the transaction immediately, while this model keeps the purchase connected to future dates. That continuing obligation is the app’s real practical effect. It can smooth cash flow, but it can also make several separate purchases overlap if I use the service casually.
What using it involves at checkout
The usual workflow begins with choosing an item from a participating retailer and selecting Afterpay when it is offered as a payment method. The app then becomes useful for reviewing the purchase arrangement and keeping an eye on upcoming payments. I would not treat the approval of one purchase as a guarantee that every later purchase will be equally suitable. Each new order should be judged against the money already committed.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
A helpful habit is to open the app before shopping, rather than only after finding something tempting. I can use that moment to check existing commitments, decide what amount is genuinely available, and set a personal limit for the purchase. This small pause reduces the risk of confusing a smaller first payment with a cheaper product.
The app’s current version is 1.140.0, and it supports devices running Android 7.0 or later. That makes it accessible on many older Android phones, although the experience can still depend on the device, operating system condition, and the retailer’s checkout flow. I would keep the application updated where possible, especially when using it for payment-related tasks.
A realistic example: replacing a necessary item
Imagine that my everyday headphones stop working shortly before a busy week. I find a suitable replacement at a store that accepts Afterpay, but paying the entire amount immediately would leave less room for transportation and food. Splitting the purchase could be reasonable if I already know that the later scheduled payments fit my pay cycle.
In that situation, I would first write down the full cost, then check the dates and amounts shown in the app. I would also ask whether I could buy a less expensive model with a normal card and avoid another future commitment. If the replacement is genuinely needed and the schedule remains comfortable after accounting for regular expenses, Afterpay offers a practical middle ground.
The same approach works better for planned household purchases than for impulse shopping. A replacement charger, school item, or work-related necessity has a clear purpose. A last-minute fashion purchase made only because the first payment looks small is much harder to justify. The best use is a planned purchase with a known repayment path.
Three habits that make the service easier to manage
First, I would group commitments mentally by pay period rather than by individual order. Several small installments can look harmless when viewed separately, yet become uncomfortable when they all arrive around the same week. Looking at the calendar as a whole gives a more honest picture than checking one order at a time.
Second, I would keep a record of the total amount, not just the next installment. A note in my budget with the retailer, total, and remaining schedule is useful because it prevents the app from becoming the only place where I remember an obligation. This is particularly valuable when I use more than one shopping service or pay for several household needs at once.
Third, I would leave a buffer. A schedule that works only if every other expense goes perfectly is already too tight. Unexpected travel, a higher utility bill, or a delayed paycheck can turn a convenient arrangement into a stressful one. The flexibility is most useful when it supplements a stable budget, not when it is being asked to rescue one.
Where the experience can feel less straightforward
Afterpay’s appeal is strongest when the purchase and the repayment plan are easy to understand. The friction appears when I need to reconcile several orders, remember different dates, or decide whether a discretionary item deserves another commitment. The app can display payment information, but it cannot make the underlying budget decision for me.
I would also pay close attention to the checkout details shown for each order rather than assuming every retailer presents the experience in exactly the same way. The store, the item, and the account situation can all affect what is available at the moment of purchase. If the arrangement does not look clear, I would stop and review it instead of rushing through checkout.
That is an important difference between a payment app and a traditional debit card. With a debit card, the main concern is whether the money is available now. With Afterpay, I must also consider whether the money will remain available later. For someone who already tracks future bills carefully, this may be manageable. For someone who often forgets subscriptions or relies on an uncertain income, the extra layer may create more trouble than convenience.
How it compares with paying normally
Paying with a debit card is usually simpler because the purchase is settled immediately and there is no continuing installment schedule to monitor. If I have enough money set aside and the purchase is not a strain, the normal payment method may be the cleaner choice. It avoids the temptation to spread several purchases across future income.
A credit card can offer a similar delay between buying and paying, but it generally places the responsibility on a statement balance rather than a purchase-specific schedule. Afterpay is easier to understand for someone who prefers seeing a defined arrangement for a particular order. On the other hand, a credit card may be more familiar for recurring expenses or situations where I need one consolidated statement, depending on my own financial habits.
Saving first remains the strongest alternative for nonessential purchases. Waiting removes the risk of overlapping commitments and gives me time to decide whether I still want the item. Afterpay is more compelling when timing matters and the purchase is already justified, not when it is being used to manufacture room in an otherwise empty budget.
Who benefits most from the app
I think Afterpay suits shoppers who have predictable income, understand their regular expenses, and want a clearly divided way to handle an occasional planned purchase. It can be especially useful when a single payment would be awkward but the full cost is still affordable across the scheduled period. The service also makes sense for people who prefer seeing a purchase broken into defined amounts instead of carrying a general revolving balance.
It is less suitable for anyone who frequently misses due dates, has irregular income, or already has several payment plans active. I would also be cautious if I tend to shop when stressed or use checkout financing to avoid looking at the full price. In those cases, paying upfront or waiting until the money is saved may provide better protection.
The app has a 4.0 average from around 169 thousand ratings, with more than 10 million installs. Those figures suggest that the concept has broad reach, but popularity should not decide whether it fits my finances. A widely used payment method can still be the wrong choice for a person whose monthly cash flow is unpredictable.
What I would check before installing and using it
Because it is free, the main cost of trying the app is not a download fee; it is the responsibility of managing the commitments created through it. I would install it only after deciding what kind of purchases I want it for. Setting that rule in advance is more effective than making a decision while looking at a sale or a full shopping basket.
I would also check the app before each new order, even if a previous purchase went smoothly. The important question is how the new schedule fits alongside existing ones. A quick review of upcoming payments can prevent the common mistake of evaluating affordability one order at a time.
Finally, I would keep normal payment methods available. Afterpay should be one option in my shopping routine, not the only way I can afford ordinary goods. If using it becomes necessary for groceries, bills, or repeated essentials, that is a sign to pause and reassess the broader budget rather than simply adding another installment plan.
Connectivity, travel, and the checkout moment
Because a purchase involves a retailer’s checkout and payment information, I would use Afterpay when I have a dependable connection rather than relying on a rushed moment in a weak-signal area. In a shop, that means checking the displayed schedule before I reach the counter; when ordering from home, it means giving the checkout enough time to load and reviewing the final details before confirming.
On a phone, convenience is also the main trap: it is easy to move from browsing to a commitment while distracted or on the go. I would save non-urgent items for a calmer moment, when I can compare the total with my budget and read the payment dates properly. That small pause is more useful than trying to make a financial decision while multitasking.
If a payment or screen does not load as expected
A slow connection or interrupted checkout can leave me unsure whether an action completed. Rather than tapping repeatedly or immediately starting a second order, I would wait for the app or retailer page to respond, then check the order and payment information before trying again. This avoids turning a temporary connection problem into duplicate confusion.
If the information remains unclear, I would stop the purchase until I could review it reliably. A payment arrangement is not the place to guess whether a screen is current. I would also keep my own budget note, so a temporary app or network issue does not leave me depending on memory to track what I owe.
Using the app without losing sight of data
Payment-related tasks naturally involve personal and financial information, so I prefer to handle them over a connection I trust and to keep access to my phone protected. I would avoid entering details while someone is looking over my shoulder or when I am distracted in a public place. These are simple habits, but they matter more here than they would while casually browsing products.
For shoppers mindful of mobile data, I would do browsing and comparison on a suitable connection where convenient, then use the phone when I am ready to review the actual checkout. The key is not to rush through the payment screen to save time or data: understanding the total and schedule is more important than finishing quickly.
My recommendation after focusing on the core feature
Afterpay is at its best when it gives a well-planned purchase a manageable schedule without hiding the full responsibility. I like the straightforward idea of dividing a cost, and I can see why shoppers appreciate having an alternative to paying everything at once. The app is focused enough to be approachable, and its shopping purpose is clear from the first use.
Still, convenience should not be confused with savings. The product does not become less expensive merely because the payments are smaller, and overlapping schedules can quietly reduce future spending room. My recommendation is to use it for occasional, necessary, or carefully planned purchases, while keeping the total cost visible and leaving space for unexpected expenses.
With that mindset, Afterpay can be a useful addition to a shopping routine. Without it, the same feature can encourage purchases that would have been postponed for good reason. I would recommend giving it a try to a disciplined shopper who wants structured payment timing; I would steer an impulse buyer or financially stretched user toward saving first and paying normally.
Pros
- Flexible payment options enhance budgeting.
- No interest or hidden fees if paid on time.
- User-friendly interface for easy navigation.
- Wide range of partnered retailers available.
- Instant approval process for quick access.
Cons
- Late fees apply if payments are missed.
- Spending limits may restrict purchases.
- Requires personal info for account setup.
- Not all stores accept Afterpay.
- Potential for overspending if not careful.
FAQs for Afterpay: Pay over time
What is Afterpay and how does it work?
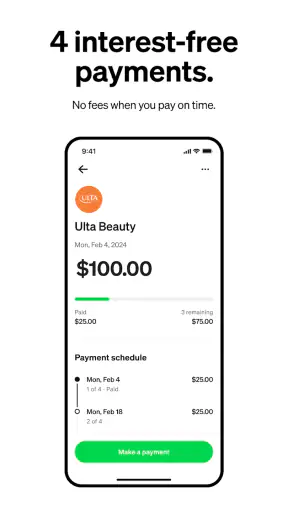
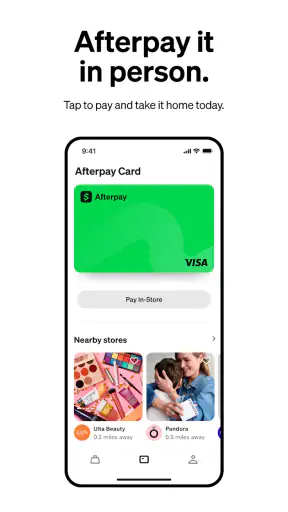
Afterpay is a digital service that allows you to purchase items now and pay for them in four equal installments over time. Once you download the app, you can shop at participating retailers both online and in-store. Afterpay pays the retailer upfront, while you make interest-free payments every two weeks.
Are there any fees associated with using Afterpay?
Afterpay does not charge any interest or fees if payments are made on time. However, if you miss a payment, late fees may apply. It’s important to ensure you have enough funds in your account on the due dates. The app will send reminders to help you avoid any potential fees.
How can I manage my payments with Afterpay?
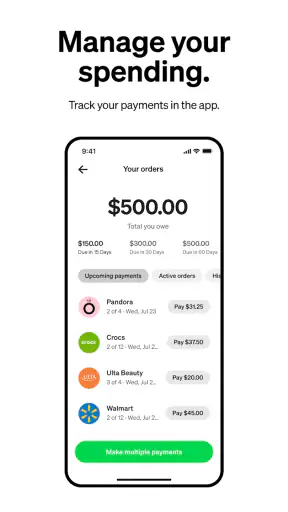
The Afterpay app allows you to track your spending, view upcoming payments, and make early payments if desired. You can also update payment methods and view your purchase history. Notifications and reminders are sent to help you keep track of your payment schedule, ensuring you never miss a due date.
Is there a spending limit with Afterpay?
Yes, Afterpay sets spending limits for users based on a variety of factors, including how long you’ve been using the service and your payment history. New users typically start with lower limits, which can increase over time as trust is built with consistent, timely payments.
Can I return items purchased with Afterpay?
Yes, items purchased with Afterpay can be returned according to the retailer’s return policy. Once the return is processed by the retailer, Afterpay will adjust your payment plan accordingly. If a full refund is issued, any payments made will be refunded directly to your payment method.

Afterpay: Pay over time
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via info@afterpay.com.au, visit https://www.afterpay.com, or review their https://www.afterpay.com/en-US/privacy-policy.










